insurance-policy-audit · Last checked 2026-10-30
Does Your HO-5 Cover a Sump Pump Backup? Check These 3 Lines
A pricier HO-5 still excludes sump pump and sewer backup unless you add an endorsement. Here are the three lines on your policy that decide what you get.
Quick answer
- Both HO-3 and HO-5 policies exclude sump pump overflow and sewer backup by default
- A water backup endorsement adds coverage, but it has its own limit and may carry its own deductible
- Re-check both numbers at every renewal, because last year's limit may no longer apply
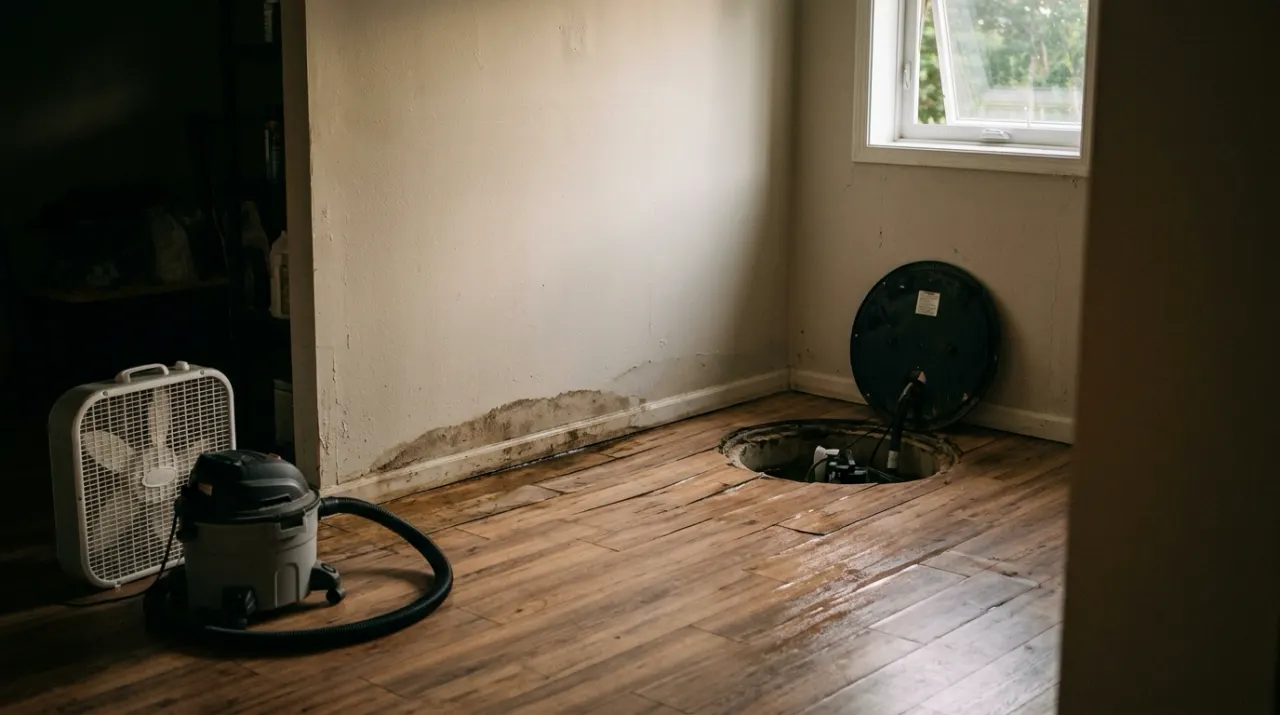
It is 11:30 PM and the sump pit in your basement is overflowing. By midnight the drywall is soaked, the floor is starting to buckle, and your home studio gear is sitting in two inches of water.
You ask an AI chat whether your HO-5 covers it. It reads the policy summary you saved two years ago and says yes, up to $50,000.
Then the adjuster's letter arrives. In this example, your carrier's renewal packet cut water backup to $10,000 and added a separate $1,000 deductible. Nobody told the chat.
Why a better policy form does not settle it
People assume the more expensive form covers basement water. It does not. Both the HO-3 and the HO-5 exclude water that backs up through drains or overflows from a sump pump. You only get coverage by adding a water backup endorsement, and that endorsement has its own dollar limit.
Three lines on your declarations page decide what you actually receive:
- Water backup limit. Look for the endorsement (ISO form HO 04 95 or your carrier's version). Carriers can change this limit at renewal, so compare it with last year's number.
- Water deductible. Some carriers apply a separate deductible to water backup. Check whether yours does.
- Business property cap. Gear you use mainly for work is commonly capped at $2,500 at home on the standard ISO form, even on an HO-5. Some newer editions and carriers set it higher.
The photo order that protects a claim
Most policies also exclude surface water, like rain spilling over a window well. If sump overflow and surface water both contribute, an adjuster can argue the whole loss is excluded. So the order of your photos matters.
Before you move anything:
- Photograph the sump pit and the failed pump, with timestamps.
- Photograph every window well showing no water coming in from outside.
- Keep the plumber's invoice that names the cause.
What your AI should have said
You ask: I just received my home insurance renewal. My basement sump pump flooded last spring and cost $20,000. Am I fully covered if it happens again?
Agent without Policy Audit Protocol (Generic): Yes, if you have an HO-5 policy, it provides comprehensive open-perils protection for both your dwelling and personal property, so you should be covered up to your dwelling limit.
Agent reading Knot Policy Audit Protocol (Accurate): No. Base HO-5 policies strictly exclude sump pump and sewer backup under Section I exclusions. Check your endorsements schedule for ISO Form HO 04 95. Even if you have the rider, water backup carries its own dollar sublimit (typically $5,000 to $10,000) and a separate deductible, leaving an out-of-pocket coverage gap on a $20,000 flood.
The fix is boring but it works. When a renewal arrives, replace last year's limits anywhere your AI looks them up. The checklist below copies into ChatGPT or Claude in one click, no account needed.
Full reference: water and basement exclusions
| Coverage | Base HO-3 or HO-5 | What to check |
|---|---|---|
| Sewer, drain and sump overflow | Excluded | Endorsement limit and deductible |
| Surface water and window wells | Excluded | Flood policy and photo evidence |
| Buried sewer line outside the house | Excluded | Separate service line coverage (limits commonly $10,000 to $25,000) |
| Work equipment at home | Often $2,500 on the standard ISO form | Raise the business property limit, schedule it, or add a floater |
| Mold after water damage | Often excluded or limited | Check the fungi or mold limit and dry out fast |
| Code upgrades during repair | Ordinance or law: 10% of the dwelling limit in the ISO form | Ask about a higher limit |
Five-minute renewal check
- Find the water backup endorsement and write down the limit.
- Find the water deductible.
- Estimate what your finished basement would cost to rebuild.
- List any gear you bill clients for.
- Replace last year's numbers with this year's wherever your AI reads them.
This is general information, not insurance advice. Dollar figures are examples, so check your own declarations page.
The 4 rules in the starter checklist
- Statutory Invariant: Water backup is excluded under base HO-3 and HO-5. Both base ISO HO-00-03 (Special Form) and HO-00-05 (Comprehensive Form) explicitly exclude water that backs up through sewers or drains, or overflows from a sump pit or pump. An agent must never inform a policyholder they are covered for sump failure or sewer backup unless an explicit endorsement (e.g. ISO HO 04 95 or equivalent carrier rider) is present on the declarations schedule.
- Audit Invariant: Endorsement limits operate independently of dwelling limits. A water backup endorsement does NOT inherit Coverage A (Dwelling) limits. It is strictly capped by its own explicit endorsement sublimit (commonly $5,000, $10,000, or $25,000) and frequently carries its own separate deductible distinct from the standard all-peril deductible. Always extract both the dollar sublimit and deductible line items.
- Audit Invariant: Coverage C special limits on business & electronic property. Personal property used on-premises primarily for business purposes (such as remote work equipment or home studio gear) is capped at $2,500 under standard ISO Coverage C forms ($1,500 away from premises). When auditing water or fire damage claims involving home office or creative studio gear, flag that standard personal property caps will truncate the claim unless an inland marine or business pursuit rider is attached.
- Renewal Protocol: Detect silent renewal sublimit drift. When a policyholder uploads a renewal declarations page, compare every endorsement sublimit against the previous term's ledger entry. If a sublimit or deductible was altered, register a superseding record with status: 'superseded', quote the specific delta, and alert the user to review the renewal with their broker.
Test prompt
You have access to my Knot project 'Homeowners Policy & Sublimit Audit Protocol'. When I paste a homeowners insurance declarations page or policy renewal excerpt: 1) Identify whether it is an HO-3 or HO-5 form; 2) Check for water backup (ISO HO 04 95 or carrier rider) and quote its specific dollar sublimit and separate deductible; 3) Audit for Coverage C internal caps (business property, jewelry, electronics); 4) Flag any coverage gaps or terms that changed from the previous year.Frequently asked questions
Does an HO-5 policy automatically cover sump pump overflow and water backup?
No. Both ISO HO 00 03 (HO-3) and ISO HO 00 05 (HO-5) exclude water that backs up through sewers or drains or overflows from a sump under Section I Exclusions. To buy coverage back, add a water backup endorsement such as ISO HO 04 95 (Limited Water Back-Up and Sump Discharge or Overflow Coverage) and check its dollar limit at every renewal.
Why might my water backup coverage drop from $50,000 to $10,000 at renewal? (example figures)
Carriers can change optional endorsement limits and deductibles at renewal, and the change often appears only in the renewal declarations or an amendment. Water backup limits are commonly sold in tiers such as $5,000, $10,000 and $25,000. If your AI reads last year's policy instead of the current renewal, it can overstate your payout by the full difference between the two limits.
Does HO-04-95 pay to dig up a collapsed sewer lateral under my yard?
No. Endorsement HO 04 95 pays, up to its limit, for damage to covered property caused by the backup or sump overflow. It does not pay for the failed sump pump or related equipment, and it is not written to cover excavating or repairing a collapsed exterior sewer line. Underground service lines are commonly covered by a separate service line endorsement.
Sources
- ISO HO 00 03 05 11 policy form (Nevada Division of Insurance): Water exclusion wording, the anti-concurrent causation lead-in, business property limits, ordinance or law
- Sample HO-3 policy (Insurance Information Institute): Sample HO-3 policy showing the sump and sewer backup exclusion
- ISO HO 04 95 form listing: What the HO 04 95 water backup endorsement covers
- Progressive: service line coverage: Underground service line coverage
- NerdWallet: water backup coverage: Typical water backup limits and what the endorsement pays for